 VN
 EN
06/09/2026, 02:00
Investment
How will State divestment drive the stock market?
State restructuring and divestment activities at enterprises are expected to impact the stock market beyond merely creating short-term trading waves...
More importantly, these activities could have a broad impact on the Vietnamese stock market as FTSE Russell prepares to upgrade Vietnam from a frontier market to a secondary emerging market in September.
Elevating the quantity and quality of market supply
The expected positive impact lies in introducing a series of new, high-quality stock offerings and investment opportunities with unrestricted foreign ownership limits (foreign room)...

Group III requires the State to hold over 50% to under 65%, including key petroleum importers with a market share of 30% or more, certain special telecommunications infrastructure, and mineral exploration sectors. Experts suggest Petrolimex (PLX) may divest its state ownership to below 65%. (Illustrative photo: L.M)
In the long term, supply and asset quality are paramount foundational factors to attract and retain capital flows, helping the market develop according to its targeted goals. This is separate from the direct benefits to the enterprises themselves in terms of reform, reorganization, state capital divestment, and restructuring to improve governance and operational efficiency.
At the same time, state capital representation and holding organizations—most notably the State Capital Investment Corporation (SCIC)—will gain additional capital through divestment and portfolio restructuring, creating conditions to focus on investment and capital management tasks according to approved strategies and plans.
Specifically, under Decision No. 40/2026/QD-TTg issued by the Prime Minister on August 5, 2026, which stipulates the classification criteria for state-owned enterprises and enterprises with state capital for capital restructuring during the 2026–2030 period, classification aims to continue the restructuring process based on three criteria groups.
100% State-owned group: Includes enterprises providing essential public products and services such as railways, air traffic control, postal services, and irrigation; natural monopoly enterprises in explosives, money printing, and lotteries; science and technology enterprises, key national infrastructure construction, and high-tech applications with projects worth at least 12 trillion VND; cigarette manufacturers, Agribank; or enterprises operating in key defense and security locations or vital sectors.
65% or more State holding group: Includes airport operators (such as ACV), special seaport managers and operators (such as PHP), large-scale mineral miners, animated film producers, and fertilizer businesses.
50% to under 65% State holding group: Includes major petroleum importers with a market share of 30% or more, critical telecommunications infrastructure service providers, and mineral exploration and quality assessment enterprises (excluding oil and gas).
In addition, many other enterprises have specific classification criteria to serve as a basis for capital restructuring.
Expectations for a stronger push
With the issuance of these classification criteria, Mr. Ngo The Hien - Deputy Director of the SHS Securities Analysis Center, noted expectations that state enterprise capital restructuring will be driven forward more vigorously.
So far, according to Mr. Hien, the market has undergone three IPO waves. The 2016–2018 period saw decisive execution of state enterprise equitization and divestment. During that period, the stock market was vibrant with notable transactions such as divestments at Sabeco, Becamex, Idico, Gelex, and several subsidiaries under the Vietnam National Oil and Gas Group (PVN), including Binh Son Refining and Petrochemical and PV Power... These transactions helped trigger a market boom.
"We expect Decision 40 and its implementation to continue supplying new market assets similar to previous periods in the coming time," Mr. Hien said.
Furthermore, the SHS expert cited Decision 40's provision that within 30 days starting August 5, 2026, governing bodies and state capital representatives at enterprises must issue 5-year capital restructuring plans. Notably, 20 large-scale enterprises and corporations subject to prior capital restructuring under Decree No. 57/2026/ND-CP issued by the Government on February 12, 2026 (effective February 13, 2026) include: Vinacomin (TKV), PetroVietnam (PVN), EVN, Petrolimex (PLX), Vinachem, Vietnam Rubber Group, Vietnam Airlines...
Three listed state-owned commercial banks—Vietcombank, BIDV, and Vietinbank—are also among those required to announce 5-year capital restructuring plans within the next 30 days. For VietinBank specifically, the Government mandates maintaining a minimum state ownership ratio of 65%. Currently, state capital at VietinBank stands at 64.46%. Thus, state ownership at VietinBank will need to be raised by nearly 1% to reach the minimum requirement.
According to SHS statistics covering state-owned enterprises across all three exchanges (UPCoM, HNX, HOSE), over 420 enterprises currently have state ownership ratios of 50% or higher, accounting for more than 50% of total listings. Most of these are large-scale enterprises concentrated on the UPCoM exchange.
Based on Decision 40, for fertilizer manufacturers such as Phu My Fertilizer and DDV under Vinachem, current state ownership has not reached the required 65% threshold. Specifically, DDV stands at 64%, while Phu My Fertilizer is at 59.59%. "It is highly probable that these enterprises will need to increase state capital ownership in the coming time," Mr. Hien stated.
For Petrolimex, while belonging to the group of petroleum importers holding over 30% market share, its current state capital ratio is 75.87%. Under Decision 40, the mandated ratio for this group is 50% to under 65%, meaning state ownership at Petrolimex will have to be reduced.
Additionally, several other enterprises previously announced capital reduction plans, such as Becamex (BCM). State capital at BCM currently stands at 95.44%; despite approval to reduce it to 65%, execution remains pending. Similarly, Viglacera previously planned to fully divest its 38.58% state stake but has yet to implement it...
Mr. Ngo The Hien emphasized: "We hope these enterprises will proceed with their divestment, capital increase, or capital reduction plans according to schedule in the coming period."
Benefits seen from SCIC
As one of the main entities managing and representing state capital, SCIC recently issued its restructuring plan for the 2026–2030 period. According to the plan, SCIC intends to sell its entire stake in 66 enterprises while maintaining capital holdings in 21 enterprises.
Specifically, SCIC will maintain 100% ownership at SCIC Investment One Member Co., Ltd. (SIC). Simultaneously, it plans to retain investments in major names such as Vinamilk (VNM), Sabeco (SAB), FPT, Hau Giang Pharmaceutical (DHG), Traphaco (TRA), Bao Minh (BMI), Vietnam National Reinsurance Corporation (VNR), Song Da Corporation (SJG), Trang Tien, Vietnam Pharmaceutical Corporation, and Vietnam-Oman Investment JSC...
Notably, the list of 66 enterprises where SCIC plans to fully exit spans multiple sectors, from industrial manufacturing, steel, textiles, and energy to construction, logistics, trade, and seafood.
Some notable companies attracting market interest in SCIC's divestment list include Tien Phong Plastic (NTP), Domesco Medical Import Export (DMC), Vietnam Steel Corporation (TVN), Vietnam National Textile and Garment Group (VGT), Vietnam Fisheries Corporation (SEA), Pha Lai Thermal Power (PPC), Licogi (LIC), Construction Materials Corporation No. 1 (FIC), Vietnam Construction Consultant Corporation (VGV), Vietnam Industrial Construction Corporation (VVN), and Pha Lai Thermal Power JSC (PPC)...
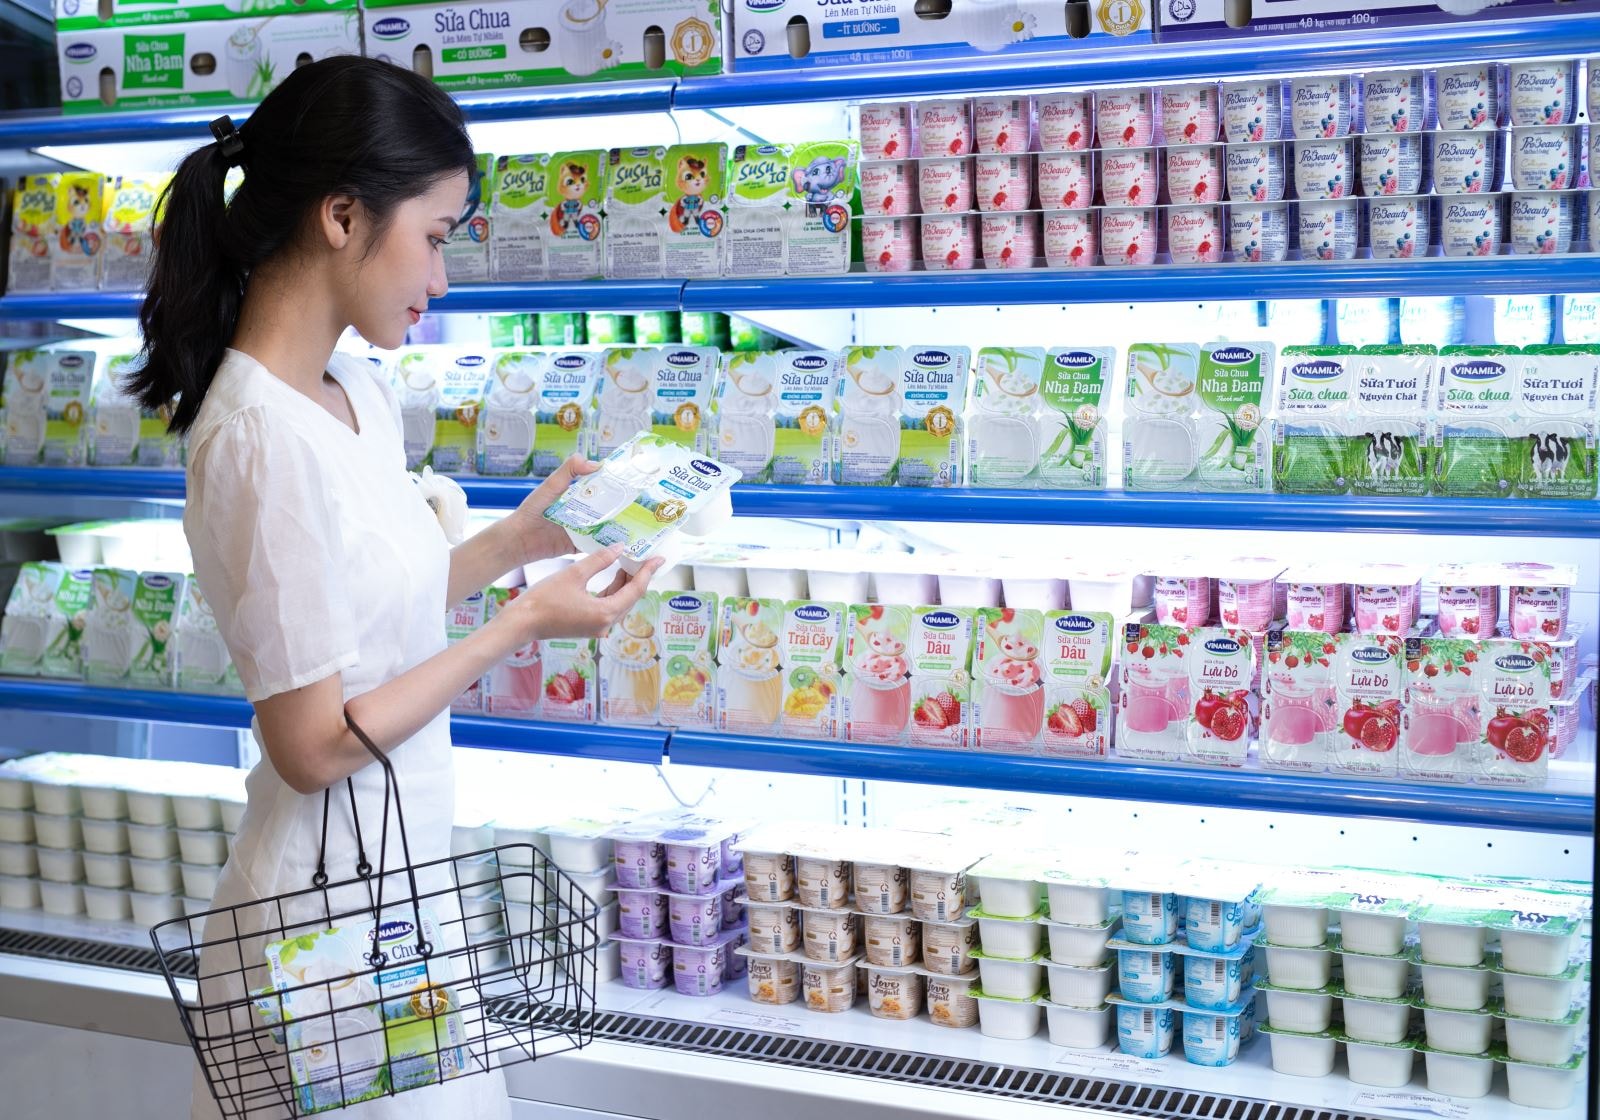
Vinamilk – an enterprise where SCIC will continue to invest and hold capital. (Illustrative photo: VNM)
Listing enterprises for full divestment provides the basis for SCIC to execute divestment schemes during 2026–2030. If executed as planned, the shares brought to market could significantly boost supply, including shares in companies with established scale and industry standing.
However, the restructuring portfolio is not fixed for the entire period. SCIC stated that the list may be adjusted based on corporate performance, market developments, and compliance classification criteria. Consequently, actual divestment progress and scale at each enterprise will depend on specific plans developed and implemented going forward.
MBS Securities assesses that Decision 40 establishes a clearer framework for state ownership, paving the way for a state enterprise capital restructuring cycle during 2026–2030.
First, it enhances transparency in state capital strategy. With clear ownership limits defined by sector, investors can better identify enterprises likely to receive state capital injections versus those with room for ownership reduction.
Second, divestment activities, if implemented, can increase free-float and liquidity while expanding opportunities to attract institutional and strategic investors.
Third, for strategic enterprises needing capital expansion, maintaining state control while allowing outside capital raising can strengthen financial capacity, particularly in banking and essential sectors.
However, according to MBS, large-scale divestments could generate supply pressure in the short term. Conversely, where the State increases ownership, free-floating shares may decrease, restricting liquidity and foreign room.
Additionally, the execution timeline remains a key variable. Issues surrounding asset valuation, land rights, and approval procedures could prolong the restructuring process.
Author: LE MY - TRUONG DANG
RELATED TOPICS
RECOMMENDED TOPICS