 VN
 EN
07/10/2026, 02:00
Investment
MCH catches the eye of foreign funds
Just a few months after listing on HoSE and fulfilling all time-related criteria, MCH stock of Masan Consumer Corporation was added to the VN30 basket. Subsequently, FTSE Russell added MCH to the FTSE Vietnam Index, placing it on the radar of numerous ETF funds.
According to estimates by SSI Research, during the September portfolio restructuring period, ETF funds could net buy approximately 4.04 million MCH shares, valued at $22.1 million.
MCH stock listed on HoSE and included in major indices.
ETFs' appetite for MCH
According to SSI Research, buying volume for MCH stock comes from major ETFs in the market, including Fubon & CSOP ETF, Vanguard ETFs tracking FTSE GEIS, and VanEck Vietnam ETF. The fact that multiple ETF groups hold the stock simultaneously—with restructuring transactions occurring right at the beginning of the process to include Vietnamese stocks in FTSE GEIS indices effective September 21, 2026—promises a new trading era for MCH since its transition to HoSE.
First and foremost, this confirms that as a leading stock in core categories of Vietnam’s fast-moving consumer goods (FMCG) market, MCH naturally attracts capital flows. Furthermore, beyond meeting growth prospects, a company must also offer room for capital absorption to trigger massive capital inflows in the near future.
Statistically, in terms of outlook, MCH currently boasts the highest profitability in the food and beverage industry, with a gross margin of 45.5%, ROE of 46.4%, and ROIC of 177% on low leverage.
Regarding room for new capital flows, MCH features a tightly held ownership structure, with 69.37% of charter capital held by Masan Group (MSN). While this structure ensures operational stability, it results in a low free-float ratio. In other words, after being vetted and held by world-leading funds like KKR, along with increasingly prominent participation from ETFs and the foreign ownership cap opened to 100%, liquidity for MCH could face an explosive phase. In particular, if the free-float ratio increases under Decree 155/2020, while the post-listing lock-up commitment of major shareholders expires by late December, foreign capital inflows across 4 roadmaps could generate even more massive trading volume for MCH.
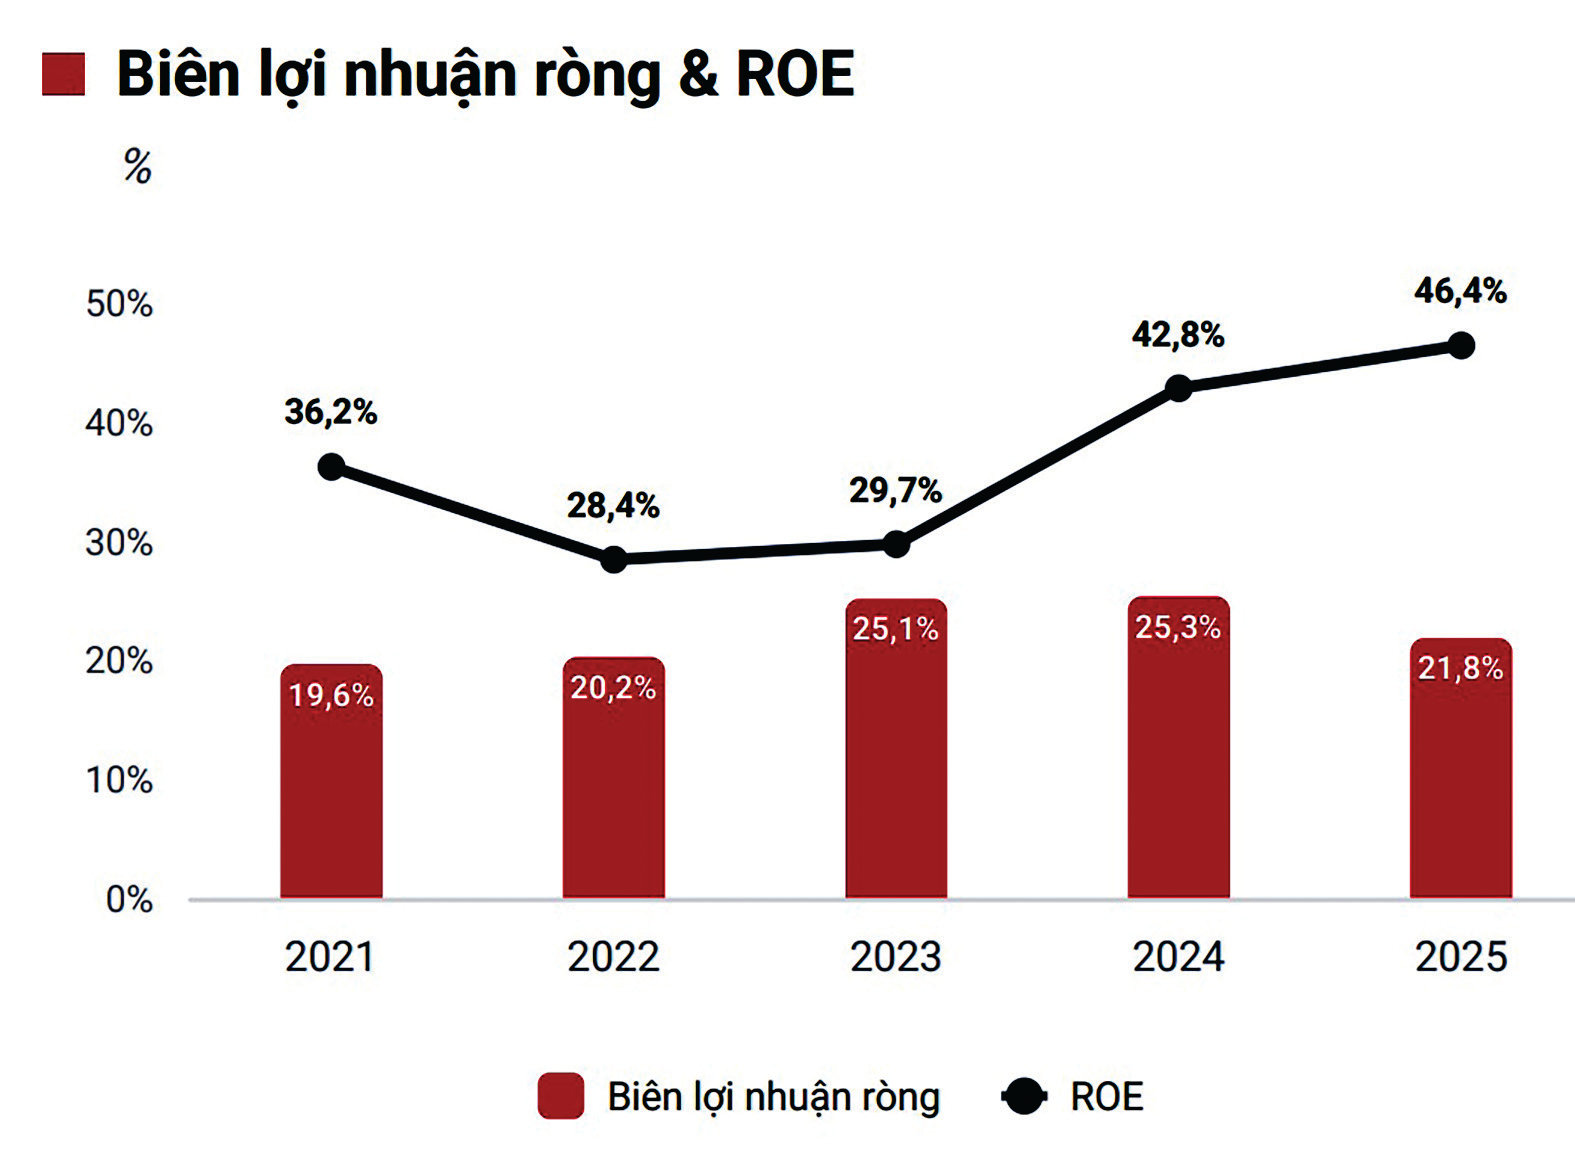
MCH's Net Margin and ROE. Source: TCBS
Foundation as a consumer food enterprise
MCH is one of the "diamond" pillars in MSN’s integrated consumer-retail ecosystem, joining forces with retail pillar WinCommerce (WCM) to create MSN's unique advantage. MCH focuses on three main priorities: the Digital 4P strategy combined with comprehensive digital transformation, product premiumization, and global expansion. Currently, MCH operates 14 factories and 16 distribution centers and directly covers 450,000 sales points as of the first 6 months of 2026—a physical footprint being digitized by Retail Supreme—alongside an upgraded, broad coverage network from WCM featuring 796 stores opened in the first 8 months of 2026, including 618 mini-supermarket outlets optimized for rural areas.
In the competitive landscape of the consumer food industry, MCH is regarded as a symbol of continuous innovation and effective R&D investment, leading the FMCG sector. Among the 35 brands it owns, MCH features 5 power brands—CHIN-SU, Nam Ngư, Omachi, Kokomi, and Wake-up 247—each generating over $100 million in annual revenue. The company also states that it possesses 16 commercial trademarks ready to conquer a global market of over 8 billion people.
In the first 8 months of 2026, MCH recorded revenue of VND 21,536 billion, a 15% increase year-over-year and closely aligned with its target plan. Omachi drove convenience food sector revenue up by 21.3%, CHIN-SU grew by 15.7%, and Nam Ngư rose by 22.4%. Bottled beverages also returned to growth at 9.5%... compared to the consumer industry's average growth rate of around 4-5%. With a premiumization strategy supported by rising income levels—as GDP per capita in 2025 surpassed $5,000 and targets $8,500 by 2030—MCH is expected to capture significant market share across consumer food categories.
Additionally, according to MSVN, the government's new tax reduction policy provides extra momentum supporting consumer recovery while reinforcing expectations of positive profit growth and market share expansion for leading modern retailers, including those within the MSN ecosystem.
TCBS considers MCH an attractive long-term investment opportunity based on its leading position, sustainable business model resilient to economic cycles, high profitability, abundant free cash flow, large dividends, and a distribution network that is difficult to replicate. The company recently paid over VND 2,614 billion for its first 2026 dividend distribution at a rate of 20% in July 2026. Between 2023 and 2025, MCH distributed approximately VND 32,000 billion (nearly $1.3 billion) in cash dividends to shareholders, underscoring both its growth and value investment potential.
Author: LE MY - TRUONG DANG (translates)
RELATED TOPICS
RECOMMENDED TOPICS